Overview of the Surface Analysis Market Scope and Industry Significance
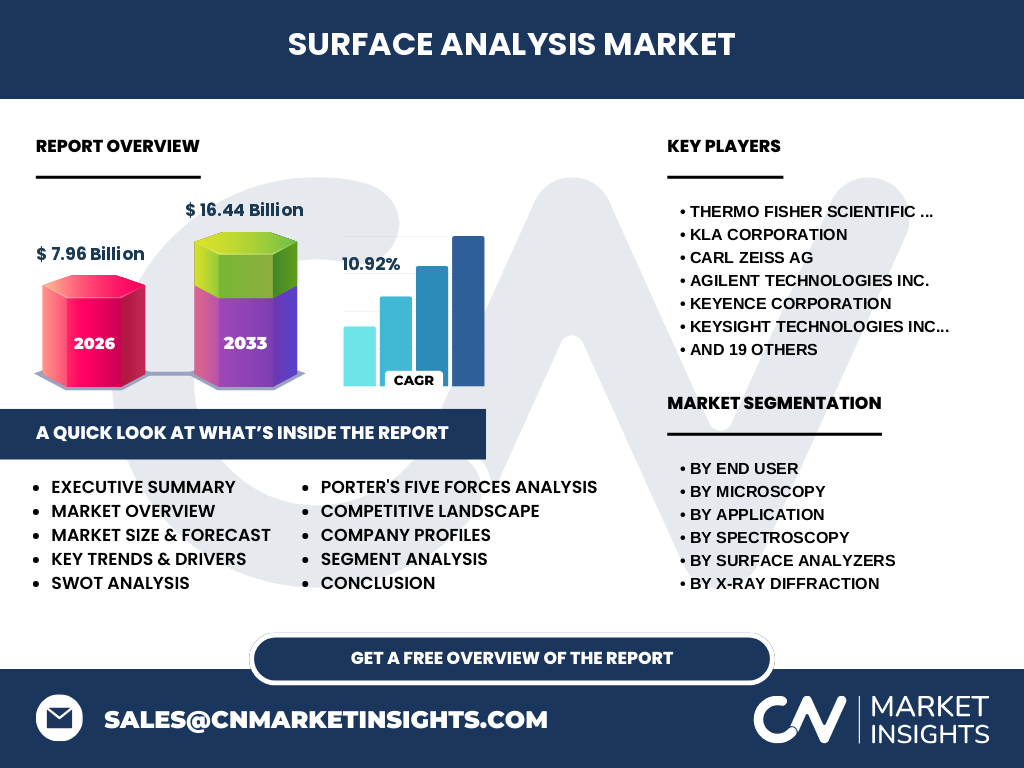
The Surface Analysis Market is a critical pillar of advanced manufacturing, focused on characterizing the topography, composition, and electronic states of materials at the nanoscale. Valued at 7.96 Billion in 2026, this sector facilitates essential breakthroughs in semiconductor fabrication, biomaterials, and energy storage. It provides the analytical rigor required by industries to ensure product performance, regulatory compliance, and structural integrity across global supply chains.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by the miniaturization of microchips and the rising demand for high-performance materials. While the 10.92% CAGR signals robust expansion, the market faces significant logistical hurdles, including strict ISO calibration standards and high entry barriers due to the sophisticated technical expertise required to operate advanced systems from entities like Thermo Fisher Scientific or Bruker Corporation.
Emerging Trends and Strategic Shifts in Surface Characterization
Industry leaders are shifting toward automated data acquisition and the integration of Artificial Intelligence for real-time image processing in microscopy. We observe a pronounced trend where firms like Carl Zeiss AG and Hitachi High-Tech are prioritizing throughput, enabling researchers to conduct high-resolution X-ray diffraction and spectroscopic analysis at speeds previously considered impossible, effectively reducing the time-to-market for novel semiconductor architectures.
How did COVID-19 redefine the trajectory of the Surface Analysis Market?
The pandemic initially disrupted supply chains for critical components like vacuum seals and detector sensors, yet it acted as a catalyst for Life Sciences innovation. Our analysis shows a significant recovery trajectory driven by increased R&D spending in vaccine development and viral surface studies, where Atomic Force Microscopy became vital. This period underscored the market's resilience, pivoting toward remote diagnostic capabilities and cloud-integrated analytical platforms.
Competitive Benchmarking and Market Concentration
The Surface Analysis Market is highly concentrated, with dominant players like KLA Corporation and Keysight Technologies setting the benchmark for precision. Competition is fierce in the spectroscopy segment, where Shimadzu Corporation and HORIBA Ltd. compete on sensitivity and noise reduction. Smaller, specialized firms like Nanosurf AG and Park Systems carve out niches by providing high-agility, high-resolution atomic force systems essential for specialized academic research.
Executive Summary: High-level synthesis of findings
With a projected growth to 16.44 Billion by 2033, the market is entering a phase of sustained technological acceleration. Key success factors include cross-platform integration and the ability to serve the dual-growth engines of semiconductor wafer inspection and nanomedicine. Our research confirms that firms adopting an ecosystem approach—pairing software with advanced hardware like Rigaku’s diffraction tools—will capture the largest market share during this forecast period.
Market Forecast: Growth Projections (2027–2033)
The market is poised for a significant climb, moving from 7.96 Billion in 2026 to a forecasted 16.44 Billion by 2033. This steady 10.92% CAGR is underpinned by the increasing complexity of wafer-level materials and the global push for renewable energy storage, which necessitates deep-level X-ray Photoelectron Spectroscopy to optimize battery electrode interfaces.
Segmentation Analysis: Categorizing Value Drivers
The market is segmented by Instrumentation Technology, covering Microscopy (SEM, TEM, AFM, STM), Spectroscopy, Surface Analyzers, and X-Ray Diffraction. By End User, the sector covers Academic Institutes, industrial manufacturers, and independent research centers. Each segment plays a specific role: Surface Profilometers remain essential for quality control in thin film production, while Transmission Electron Microscopy remains the gold standard for high-end academic discovery.
Regional Market Performance and Distribution
North America and Asia-Pacific are the twin engines of the Surface Analysis Market. While North America maintains leadership in Life Sciences applications through firms like Agilent Technologies, the Asia-Pacific region dominates in semiconductor volume, heavily influencing demand for Scanning Electron Microscopy. Europe remains a key center for precision engineering, particularly in the development of specialized goniometers and surface measurement instruments required for automotive and aerospace testing.
In-depth Regional Review: Geographic Dynamics
In East Asia, particularly Japan and South Korea, logistical clusters around major semiconductor hubs drive the uptake of JEOL Ltd. and Hitachi instrumentation. Conversely, the North American market is bolstered by DARPA-funded research and private enterprise spending in biotech, necessitating high-throughput Raman Spectroscopy solutions. Regional constraints often involve compliance with local trade regulations and export controls on dual-use sensitive analytical equipment.
Strategic Positioning of Leading Companies
Companies like Thermo Fisher Scientific focus on end-to-end laboratory automation, while Veeco Instruments Inc. specializes in the precise thin film deposition and measurement tools required by the data storage industry. Oxford Instruments plc and Renishaw plc differentiate through advanced materials characterization, offering bespoke solutions that integrate seamlessly into industrial workflows, proving that specialized application expertise is the primary differentiator in this high-barrier market.
Porter's Five Forces Analysis
The market experiences high Rivalry among established players, balanced by high Barriers to Entry due to proprietary IP in electron optics and spectroscopic signal processing. Supplier Power is moderate, limited to specialized sensor and component vendors, while Buyer Power remains high among large-scale industrial fabs that demand bespoke instrumentation technology configurations. The threat of substitution by lower-cost, simplified measurement tools remains minimal due to the extreme precision requirements of modern manufacturing.
SWOT Analysis of the Surface Analysis Sector
Strengths: Deep-rooted integration with high-tech manufacturing. Weaknesses: High capital expenditure and long installation cycles. Opportunities: Expansion into green energy materials characterization and automated AI-driven analysis. Threats: Global supply chain volatility affecting critical components like specialized lenses or radioactive sources. Addressing these strategic inflection points is vital for sustaining the 10.92% CAGR through 2033.
Value Chain Analysis: From Raw Materials to End-Users
The value chain initiates with high-purity component manufacturers and software developers, flowing through the System Integration layer where firms like Bruker and SPECS GmbH assemble, calibrate, and test analytical units. Final delivery involves high-touch logistical handling—often involving climate-controlled shipping—to semiconductor fabs and research universities, who rely on the instruments to optimize their own proprietary processes, completing the cycle of industrial value creation.
Investment Insights and High-Potential Areas
Our research indicates that the highest ROI is located in automated inspection platforms capable of integrating into smart factories. Specifically, investments in X-ray Reflectivity and Raman Spectroscopy software are high-potential areas. Capitalizing on the rise of nanotechnology in emerging markets provides an excellent growth vector for strategic M&A, particularly for companies seeking to acquire proprietary software algorithms that enhance existing microscopy product lines.
Conclusion and Key Takeaways
The Surface Analysis Market is a high-growth sector set to reach 16.44 Billion by 2033. Success hinges on a company's ability to evolve from a hardware provider to a comprehensive solution partner. The integration of AI, support for green energy research, and maintaining deep-tier industrial partnerships will be the defining factors that separate market leaders from legacy players in this competitive, high-barrier landscape.
Research Methodology: How we triangulated the data
Our estimates are triangulated using a multi-layered approach: Primary interviews with CTOs and lab directors, trade registry analysis for regional shipment patterns, and the synthesis of secondary macroeconomic indicators. We cross-reference manufacturer reported R&D spend with import/export logs from major customs zones to ensure the baseline 7.96 Billion 2026 valuation captures the true, localized intensity of instrument deployment and maintenance revenue across global markets.
Scope of the report: Parameters and Limitations
This report covers the Surface Analysis Market globally, specifically focusing on instrumentation technology including Microscopy, Spectroscopy, and X-ray diffraction. Limitations include volatility in short-term component pricing and regional variability in regulatory frameworks governing hazardous sources. The study excludes basic optical microscopy, focusing strictly on high-resolution analytical instrumentation utilized for precise topographical, elemental, and structural characterization in commercial and research settings.
Recent Developments: Partnerships and Product Launches
Recent strategic moves show a surge in collaborative innovation, such as Thermo Fisher Scientific’s recent integration of AI-based automated workflows in electron microscopy. Furthermore, new partnerships between Anton Paar GmbH and polymer research facilities have introduced standardized contact angle goniometers to the global market, illustrating the industry’s ongoing commitment to standardization and precision in increasingly diverse industrial applications.